How do I get a cash offer for my house? It's simpler than most people expect: you share a few details about the property, a buyer reviews it, and you receive an offer you can accept or decline. No listing, no showings, and no waiting on a buyer's mortgage approval. Here's exactly how it works, what to have ready, and how to make sure the offer you get is a good one.
The Short Answer: 3 Steps
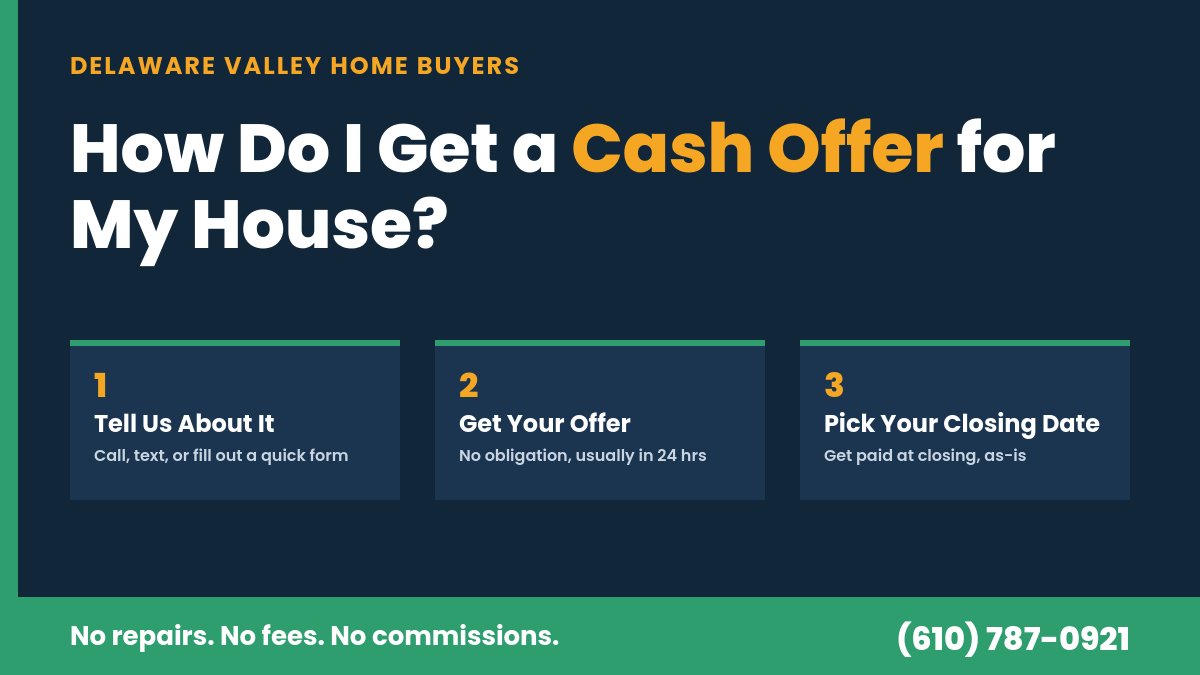
- Tell the buyer about your property. Call, text, or fill out a short form with the address and a few details about the condition and your timeline.
- Receive your offer. A local buyer reviews the property and comparable sales, then gives you a no-obligation number, usually within about 24 hours.
- Choose your closing date. If you accept, you pick the date that works for you. A local title company handles the paperwork and you're paid at closing.
4 Ways to Get a Cash Offer
Not every route works the same way. Here's an honest look at the main options:
1. A Local Cash Home Buyer
A local company buys the house directly, usually as-is. You deal with one team, get a firm offer quickly, and can often close in one to two weeks. This is the route we take at Delaware Valley Home Buyers, and it tends to work best when the home needs repairs or you're on a deadline.
2. Real Estate Investors
Individual investors and small investment groups also buy houses for cash. Quality varies a lot, so verify who you're dealing with, ask for proof of funds, and make sure the closing goes through a title company.
3. Online Instant-Offer Companies (iBuyers)
Large online platforms can generate an offer quickly, but they typically buy only homes in fairly good condition, and service fees plus repair deductions can reduce what you actually net. Always ask for the final number after all fees.
4. Agents With Cash Buyer Networks
Some agents offer a cash-buyer program as a faster alternative to a full listing. It can be a reasonable middle ground, but ask whether commission or fees still apply, since that affects your net.
What to Have Ready Before You Ask
You don't need a perfect packet, but a few details speed everything up:
- The property address
- A short description of the condition, including any major issues like the roof, foundation, or water damage
- Whether it's owner-occupied, vacant, or has tenants
- Your most recent mortgage statement, if there's a loan on the house
- Your target timeline, including any hard deadline
- Photos, if you have them (helpful, but not required)
You don't need to clean, repair, or stage anything first. Cash buyers purchase houses as they sit, so spending money before you ask for an offer usually just means spending money you don't need to.
What Happens After You Submit Your Info
- A quick follow-up. The buyer reaches out to confirm details and ask a few questions about the property.
- The property review. This may be a brief walkthrough or a photo-based review, depending on the situation.
- Your written offer. You'll receive a clear number, typically within 24 hours of the review.
- The agreement. If you accept, you sign a purchase agreement and choose a closing date.
- Closing. A title company confirms ownership, pays off any mortgage or liens from the proceeds, and pays you the remainder at closing.
How to Compare Cash Offers
The highest number on paper isn't always the best offer. When you have more than one offer, compare:
- Your net proceeds. What you actually keep after fees, commissions, and closing costs.
- Who pays closing costs. This varies, so get it in writing.
- Contingencies. A truly cash offer shouldn't depend on financing or an appraisal.
- Proof of funds. A real buyer can show they have the money to close.
- Closing timeline. Make sure the buyer can close when you need to.
- Contract terms. Look for clear, specific language, and have an attorney review it if you have any doubts.
For a closer look at the numbers, see our guide on how cash home buyers calculate their offers, and our comparison of a cash offer versus listing with an agent.
Red Flags to Avoid
Most cash buyers are legitimate, but a few warning signs mean you should slow down: asking for money upfront, pressuring you to sign immediately, refusing to show proof of funds, or wanting the deed signed before you're paid. We cover these in detail in 8 red flags of cash home buyer scams.
Frequently Asked Questions
Does it cost anything to get a cash offer?
No. A legitimate buyer gives you an offer at no cost and with no obligation. If anyone asks for an application fee or deposit before making an offer, treat that as a red flag.
How long does it take to get a cash offer?
With a local buyer, you can usually expect an offer within about 24 hours of sharing the property details. Closing is often 7 to 14 days after you accept, or later if you need more time.
Will a cash offer be as high as the market value?
Usually not. Cash offers tend to come in below full retail value because the buyer takes on repairs and risk, while you avoid commissions, repair costs, and months of waiting. Compare the net amount you'd keep from each option, not just the headline price.
Do I need to repair or clean the house first?
No. Cash buyers purchase houses as-is, so there's no need to repair, repaint, or clean out the property.
Can I get a cash offer if I still have a mortgage?
Yes. Your mortgage payoff comes out of the sale proceeds at closing, and you receive the remainder. Having a recent mortgage statement handy helps.
Do I have to accept the offer?
No. There's no obligation. Take your time, compare other options, and decide what's right for you.
Ready to Get Your Cash Offer?
If you own a house in Delaware, Chester, or Montgomery County, PA, we'd be glad to look at it and give you a straightforward, no-obligation cash offer. Call or text (610) 787-0921, or use the button below to get started. There's no cost to ask and no pressure to accept.